Written by: ChandlerZ, Foresight News
Strategy, which holds more than 850,000 bitcoins, is waiting for MSCI to publish a list that could change its shareholder structure.
Index compiler MSCI has determined that it will use a new methodology to screen out non-operating companies that do not meet the requirements of its Global Investable Market Indexes. Strategy appeared on the previously announced potential deletion list, and the final result is expected to be announced after 6 a.m. Beijing time on November 12.
Strategy, which holds more than 850,000 bitcoins with a cumulative purchase cost of more than $64.1 billion, had previously been included in the candidate deletion list. If the final list confirms its removal, globally passively tracking funds will carry out mandatory rebalancing before the close on November 30, triggering forced selling of $1.57 billion to $2.8 billion. This event will directly suppress Strategy's equity premium and block its core channel for delivering incremental buy orders to the crypto spot market.
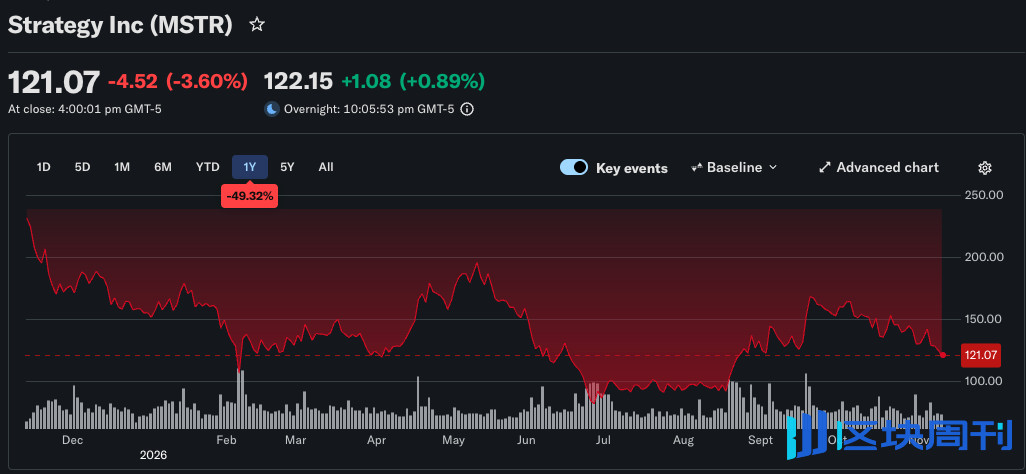
As of the U.S. stock market close on November 11 Beijing time, Strategy's common stock MSTR closed at $121.07, down 3.60% that day and about 6.4% from the closing price of $129.30 on November 5. The company disclosed on November 9 that, as of November 8, it held a total of 850,364 bitcoins, with a cumulative purchase cost of about $64.16 billion.
Why would Strategy be kicked out of the index?
MSCI's global indexes are used by a large number of funds to build stock portfolios, and whether a company can remain in the index affects passive tracking funds' holdings of that company.
Last October, MSCI proposed a deletion plan for treasury companies whose digital assets accounted for 50% or more of total assets. In January this year, it decided not to implement it in the February review for the time being and shifted to a broader review of non-operating companies.
On October 16, MSCI finalized a new index eligibility rule. Starting from the November index review, listed companies that mainly rely on holding assets for value and lack actual operating activities may be classified as "non-operating companies" and no longer qualify for inclusion in the MSCI Global Investable Market Indexes. In other words, companies such as Strategy, Metaplanet, and Upexi, which rely on capital market financing to buy coins, may no longer be regarded by MSCI as ordinary operating enterprises.
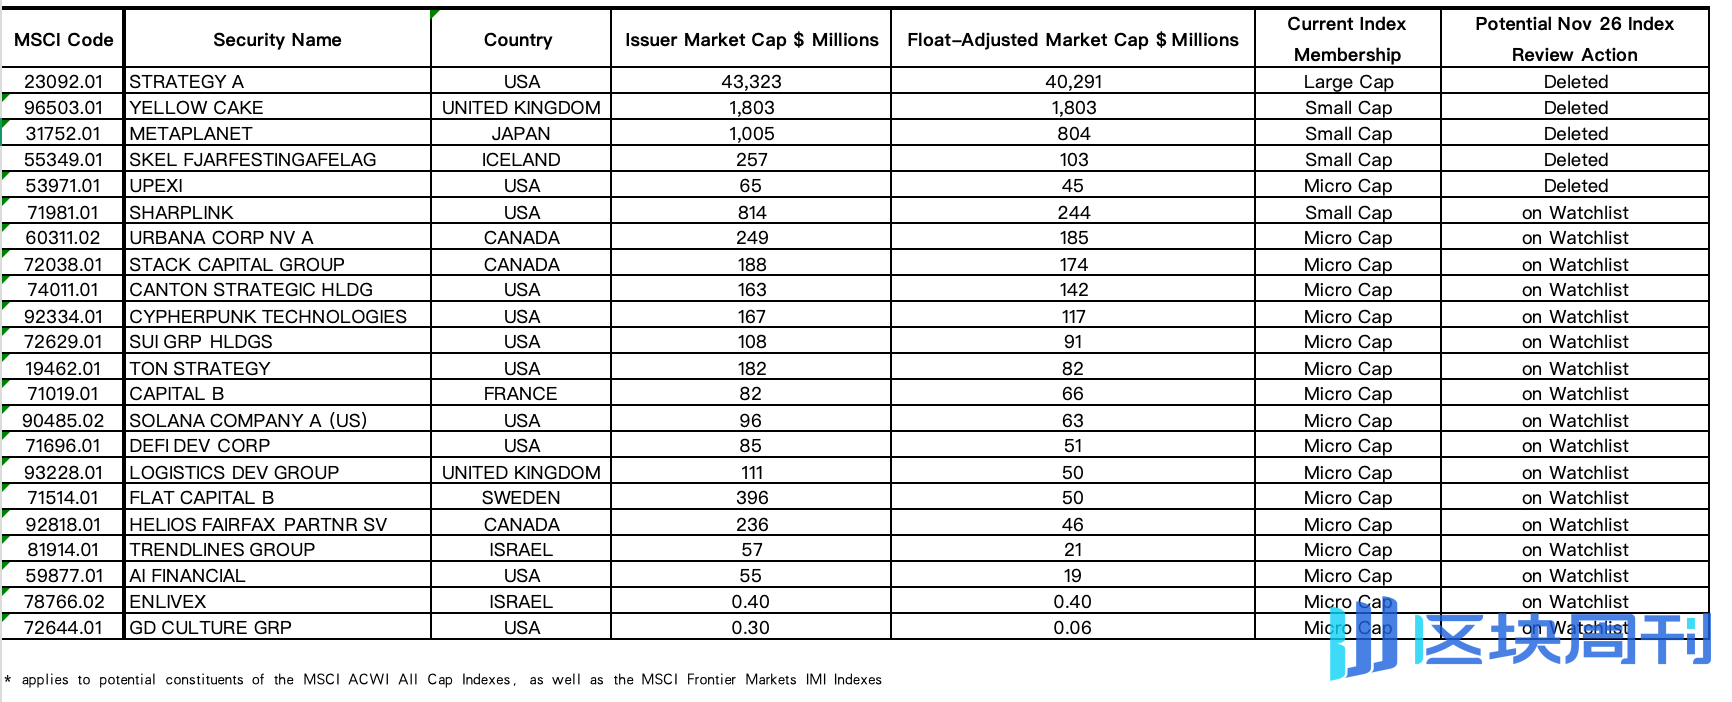
MSCI also published a list of potentially affected companies. Among the 22 companies, 14 are directly related to cryptocurrencies: Strategy, Metaplanet, and SOL treasury company Upexi were listed for proposed deletion, while another 11 companies, including SharpLink and Solana Company, entered the watch list.
The new rule first determines whether a company's asset structure contains enough operating assets. Companies that fail this threshold must also undergo checks on five financial indicators, including operating expenses, operating cash flow, changes in fair value, and reliance on external financing. If four or more are triggered, they may lose index eligibility. For companies already in the index, MSCI requires that they fail the screening in both of the most recent two annual reporting periods before they are deleted.
Among the 5 companies proposed for deletion, 3 are digital asset treasury companies:
- Bitcoin treasury company Strategy;
- Bitcoin treasury company Metaplanet;
- SOL treasury company Upexi.
The other two are British uranium investment company Yellow Cake and Icelandic investment holding company SKEL, which shows that the rule is not formally aimed only at crypto assets.
Another 11 crypto-related companies were placed on the watch list, including:
- ETH treasury company SharpLink;
- CC (Canton) treasury company Canton Strategic Holdings;
- ZEC treasury company Cypherpunk Technologies;
- SUI treasury company SUI Group;
- TON treasury company TON Strategy;
- BTC treasury company Capital B;
- SOL treasury company Solana Compan;
- SOL treasury company DeFi Development;
- WLFI treasury company AI Financial;
- RAIN treasury company Enlivex;
- GD Culture, which holds BTC and had previously announced an allocation to TRUMP.
Strategy has objected to the new methodology. The company believes that it still operates a software business and reports its bitcoin business as an operating segment in its financial reports, and that MSCI's new rule in fact once again targets digital asset treasury companies. MSCI said that the new screening methodology is aimed at companies whose financial characteristics resemble investment vehicles and that its scope is not limited to companies holding crypto assets.
Rebalancing countdown, billions of dollars in mechanical liquidation
Once Strategy is removed, its stock MSTR will directly face the selling. Funds that fully replicate the relevant index usually need to sell the constituent stocks they hold; funds using methods such as sampling replication can adjust according to their investment strategies, and the trading time and volume of different products will also vary.
A simulation model previously published by JPMorgan believes that if all sources of funds, including coordinated benchmarks, fully exit, the upper limit of passively withdrawn funds could reach $2.8 billion. Strategy's official quantitative floor is relatively more conservative. Estimates show that passive funds tracking the index hold a total of about 13 million MSTR shares, accounting for 3.1% of its total share capital, corresponding to a market value of about $1.57 billion at the current price.
Based on a simple calculation using the closing price of $121.07 on November 11, this batch of shares is worth about $1.57 billion. The company believes that this amount is lower than its then-statistical average daily trading volume and that the impact on the business is limited.
However, high trading volume does not mean that new selling pressure can necessarily be absorbed by buyers near the original price. Some investors may trade ahead of list expectations, and the actual rebalancing price also depends on whether other buyers are willing to take over. Passive funds selling MSTR will not directly sell the bitcoins on Strategy's balance sheet, which are still held by the company.
Will a stock price decline transmit to Bitcoin?
The real lethal power of passive funds' exit for the crypto market lies in breaking Michael Saylor's arbitrage loop built on U.S. stock market liquidity.
Strategy's coin-buying model over the past four years has been able to work entirely because of the long-term large premium of its stock trading price relative to the underlying bitcoin net asset value (mNAV). As long as the premium exists, the company can use the at-the-market (ATM) offering mechanism to sell common stock at high prices in the U.S. stock market, or even issue low-interest convertible bonds in exchange for U.S. dollar cash. These raised fiat currencies are unidirectionally injected by management into the crypto spot market to sweep the market and build positions. The rapid expansion of bitcoin reserve scale further stimulates speculative sentiment among retail investors and hedge funds, pushing up the stock premium and enabling the next round of larger-scale equity financing.
Just between November 2 and 8, Strategy had just sold 2.05 million MSTR shares through this mechanism to raise $283.8 million, and then immediately converted $81.9 million of it into 1,036 bitcoins in spot.
If removal brings sustained selling pressure, MSTR's stock price and valuation may be affected, and the amount of funds the company can raise for each share sold in future equity issuance will also decrease. To raise the same amount of money, Strategy may need to issue more shares, and the proportion held by existing shareholders will decline accordingly. If investors also demand higher returns, the company's cost of financing through preferred shares or debt may also rise.
For financing pressure to further transmit to Bitcoin, it would require links such as the company reducing future purchases, selling existing assets, or other investors simultaneously adjusting positions. Index removal alone cannot lead to the conclusion that Strategy must sell coins, nor can it calculate how much Bitcoin would fall as a result.
However, Strategy has already sold Bitcoin this year. The company disclosed that approximately $431.8 million of the proceeds from some Bitcoin sales this year were used to support preferred stock dividends and STRC repurchases; at the same time, the company continued to buy coins. As of November 8, its U.S. dollar reserve specifically designated to support preferred stock dividends and debt interest was approximately $4.77 billion, with an additional $146.2 million in cash available for broader corporate purposes.
Even Metaplanet, Upexi, and SharpLink, among others, have copied the financial engineering playbook of issuing stock to hoard tokens. The core weakness of these companies is highly consistent, namely that their main business has weak cash-generating capacity and is extremely dependent on asset premiums in the public capital markets to sustain operations.
MSCI's qualitative standards have established a clear isolation boundary for traditional financial markets, and the mainstream index system has formally cut off the unconscious supply of passive funds to shell entities that hoard coins. If index providers such as S&P and FTSE follow suit with similar rules, the golden window for global listed companies to absorb crypto assets on a large scale through secondary-market equity leverage will face comprehensive constraints from the underlying traditional financial system.