Original | Odaily Planet Daily (@OdailyChina)
Author|Azuma (@azuma_eth)
At a time when Silicon Valley tech giants are collectively suffering from "AI capital expenditure anxiety," Apple has reclaimed the throne of the world's largest market capitalization in an almost classical manner.
Unlike tech giants such as Microsoft, Google, and Amazon, which keep ramping up data centers and computing infrastructure, Apple has consistently maintained relatively restrained capital expenditure. Relying on solid cash flow, Apple became a "safe haven" for Wall Street capital inflows during the past round of volatility over whether "AI has peaked," with its market capitalization overtaking the sold-off Nvidia and briefly reaching $5 trillion.
Measured from the low point at the end of June, Apple's stock price has risen 25% over the past four months, with its market capitalization increasing by about $1 trillion. However, standing at the $5 trillion peak, the scenery is accompanied by a chill — a forward P/E ratio as high as 36x (at the 99th percentile of its own history, roughly twice that of the S&P 500) means the market has already priced Apple's certainty premium to the extreme, greatly narrowing the margin for error.
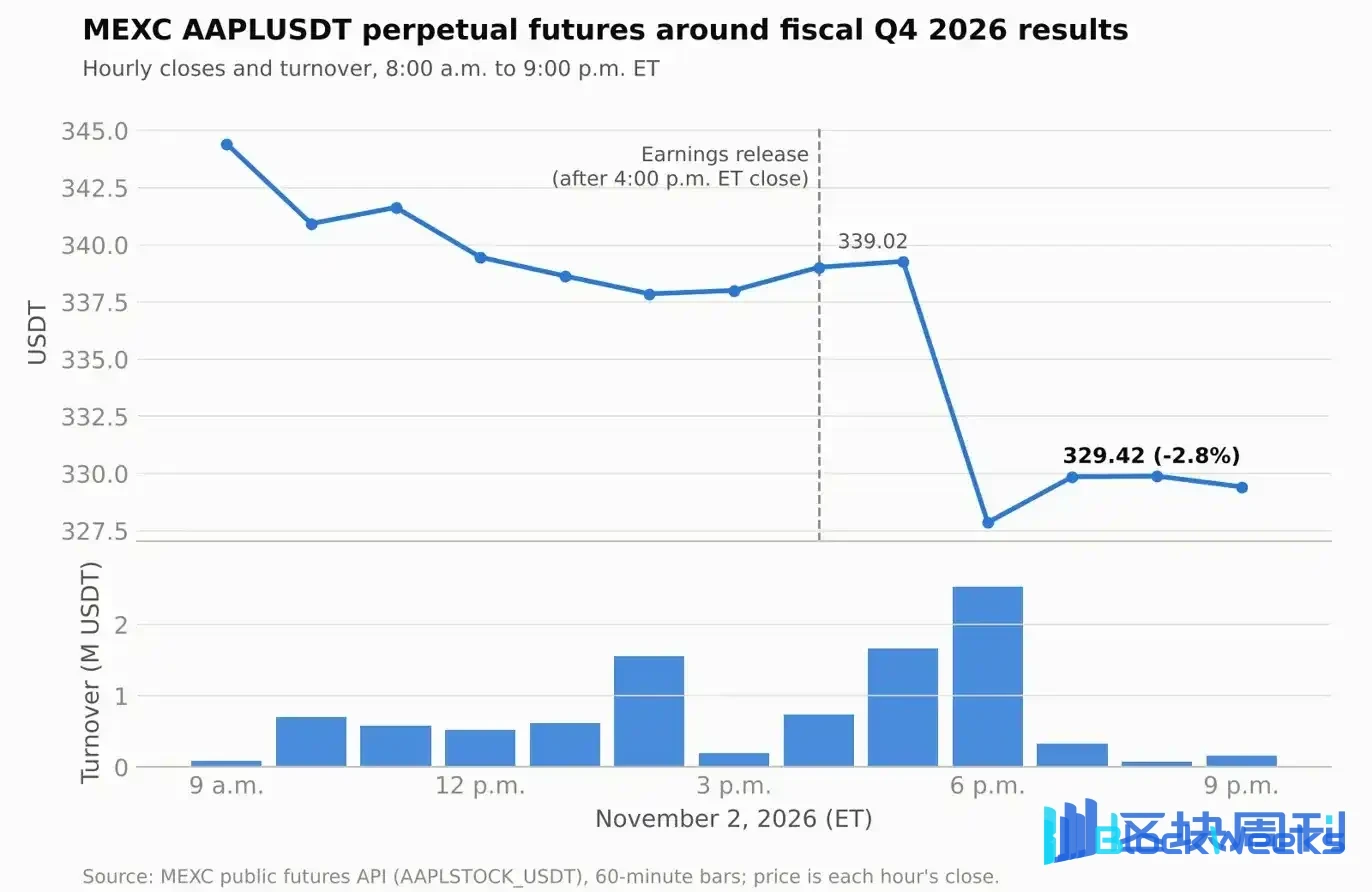
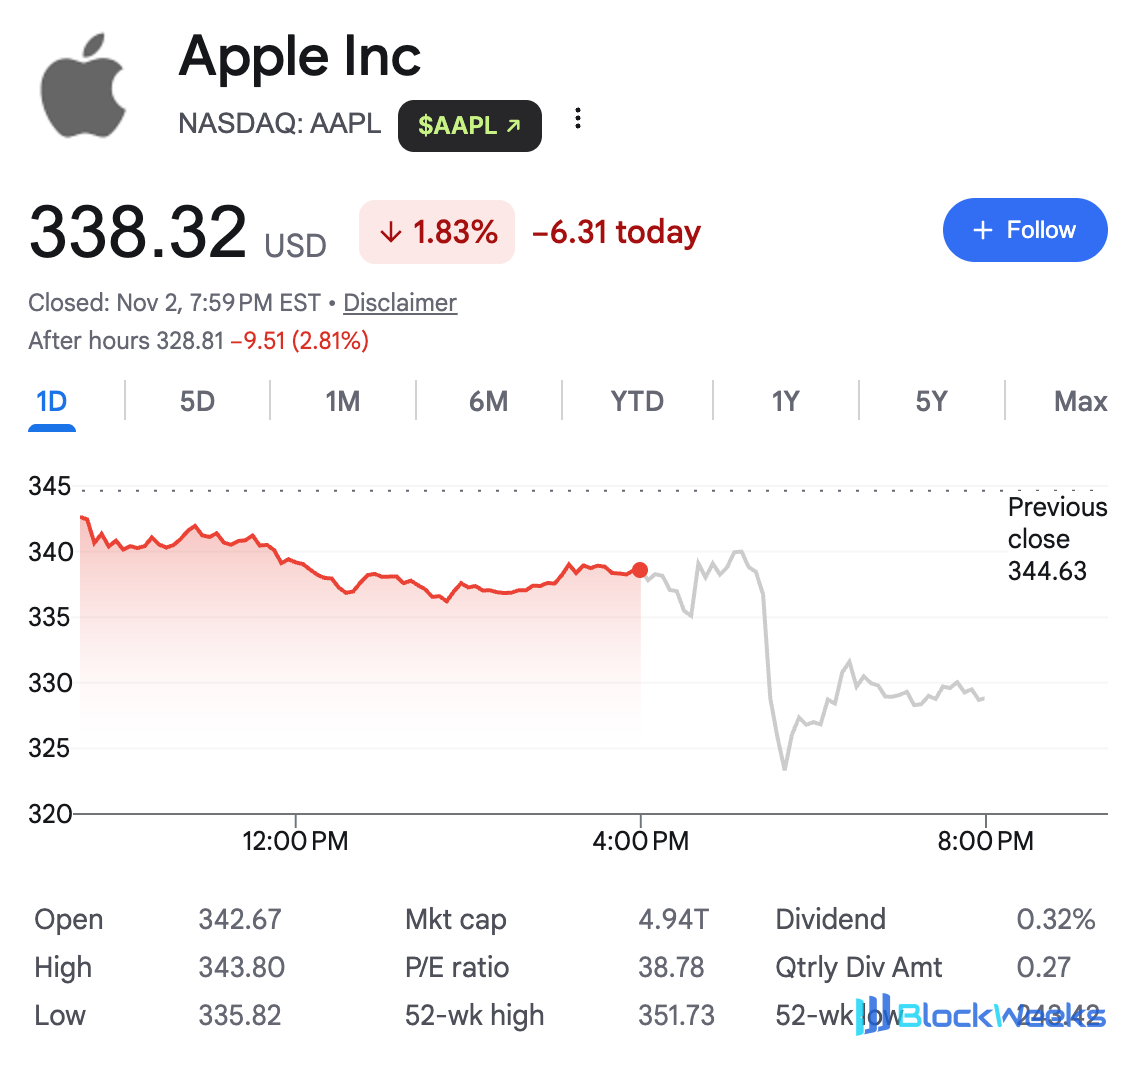
After U.S. market close on November 3 Beijing time, John Ternus, who just succeeded Tim Cook as Apple CEO in September this year, delivered his first earnings report since taking the helm (Q4 and full-year results for fiscal 2026). Although both revenue and net profit beat Wall Street expectations, Apple's stock price briefly rose 0.4% after hours before quickly plunging, at one point falling more than 4%. As of 9:30 Beijing time on November 3, the stock was temporarily at $328.81, down 2.81% after hours.
The post-market divergence in consensus essentially reveals the deeper game beneath the "safe haven" narrative — when the prosperity on the books meets the memory chip price increase cycle and the structural deceleration of the services ecosystem, the crown on Apple's head is facing its first real stress test.
$136.1 billion in free cash flow: the foundation supporting a $5 trillion market cap
Looking only at core financial indicators, Apple's fiscal 2026 has actually drawn a rather beautiful conclusion.
The earnings report shows that in the fourth fiscal quarter ended September 26, 2026, Apple achieved total revenue of $114.477 billion, up 11.72% year-over-year, not only above the market expectation of $113.47 billion but also breaking through the upper end of the company's previously provided guidance range of 9% to 11% growth; quarterly net profit came in at $30.711 billion, up 11.81% year-over-year; diluted earnings per share (EPS) reached $2.1, up 13.51% year-over-year, exceeding the market expectation of $2.
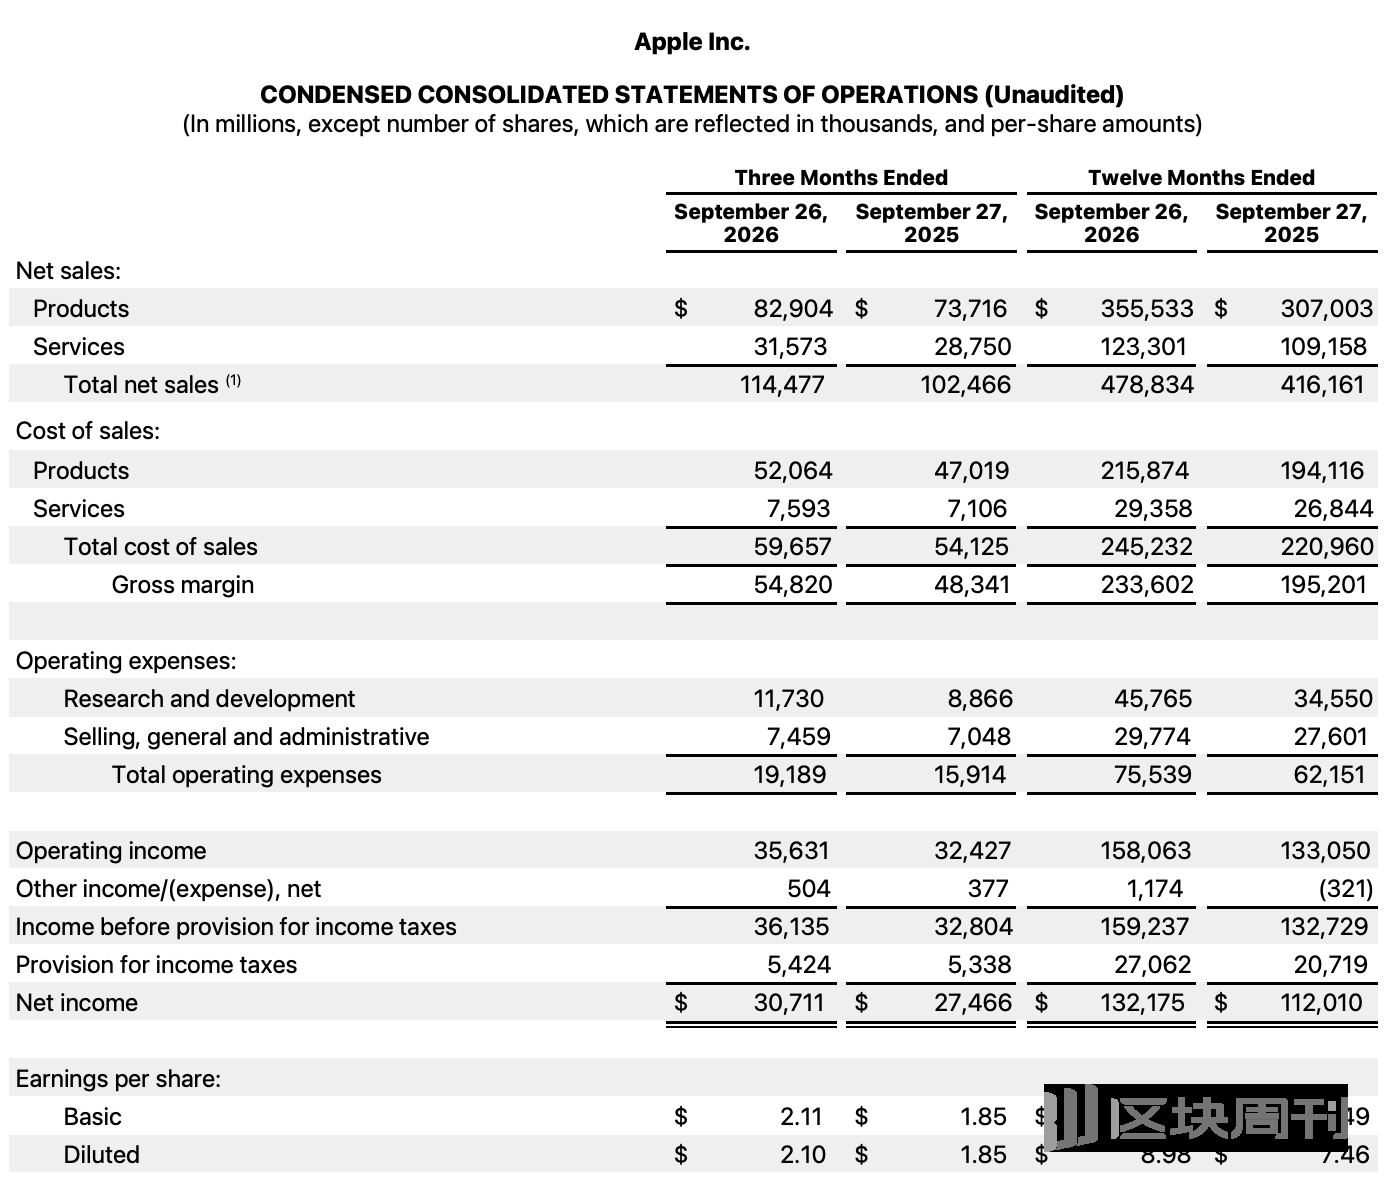
Across the entire fiscal 2026, Apple's full-year total revenue reached a record $478.834 billion, up 15.06% year-over-year, marking its best annual sales growth since 2021; full-year net profit reached $132.175 billion, up 18.00% year-over-year.
At a time when tech stocks are jittery, the core trump card that enables Apple to beat Nvidia and return to the top of market capitalization is written in the cash flow statement. In fiscal 2026, cash flow from operating activities reached as high as $145.097 billion, surging 30.15% year-over-year. What is even more striking to Wall Street is that while Google, Meta, and Amazon spend lavishly and even fall into free cash flow deficits in their fight for AI computing supremacy, Apple's full-year capital expenditure (CapEx, i.e., cash spending on fixed assets) not only did not expand but actually shrank nearly 29% from $12.715 billion in fiscal 2025 to $9.041 billion.

The model of "high revenue conversion + light capital expenditure" allowed Apple to rake in $136.056 billion in free cash flow in fiscal 2026, surging nearly 38% year-over-year, and supported the company in completing $86.390 billion in share buybacks and $15.721 billion in dividend payouts for the full year — in a cycle where the returns on AI commercialization remain unclear, this massive money-printing machine has become the most scarce certain asset in the eyes of institutional investors.
iPhone still carries the load, but hardware divergence intensifies
Peeling away the shell of total revenue beating expectations, Apple's hardware fundamentals this quarter show a distinct pattern of "dual-core drive, two wings stalling."
The banners of growth this quarter are iPhone and Mac. In the fourth fiscal quarter, the iPhone business contributed $57.583 billion in revenue, up 17.46% year-over-year, setting a record high for the September quarter and exceeding the market expectation of $56.49 billion; the Mac business was even the biggest surprise of the quarter, with revenue surging 23.68% year-over-year to $10.792 billion, far exceeding Wall Street's expectation of $9.7 billion.

It should be noted that this quarter's iPhone 18 Pro series did not officially go on sale until September 18, only about nine days before the end of the fiscal quarter. Therefore, this earnings report has not actually fully reflected the complete sales performance of the new-generation iPhone. As for the highly anticipated iPhone Duo, although Apple announced this product in September, its official on-sale date is October 23, later than the end date of this quarter's earnings report. Therefore, iPhone Duo did not contribute to this quarter's revenue, and its true market performance will only be reflected in the next fiscal quarter.
Judging from the current situation, iPhone Duo has received an enthusiastic market response after launch, but there have also been reports that some early users encountered screen cracking and display failure issues. Turnus admitted at the conference call that the model is currently in a "supply-constrained state." Although he emphasized that only a "very small proportion" of devices were returned or exchanged due to failures, ramping up production capacity and yield rates remain severe tests for the holiday season.
In other products, iPad business revenue for this quarter fell 10.40% year over year to $6.229 billion; the Wearables, Home and Accessories business, including Apple Watch and AirPods, also shrank 7.91% to $8.300 billion, both below market expectations.
By region, revenue in Greater China in the fourth fiscal quarter was $17.539 billion. Although it still maintained strong year-over-year growth of 21.02%, it fell 6.8% quarter over quarter from the previous quarter ($18.82 billion), nearly 6.5% below Wall Street's expectation of $18.75 billion. Under the magnifying glass of a PE as high as 36 times, any shortfall in core overseas markets is enough to become a reason for funds to take profits.

The Real Trigger for the After-Hours Decline: The Memory Cycle Backlash and the Loosening of the "Apple Tax"
If the flaws in Greater China and some hardware were merely ripples, then the two warnings from management on the earnings call were the direct trigger for the selloff.
The first warning is the backlash of rising memory chip prices on gross margin. On the surface, Apple's gross margin in the fourth fiscal quarter reached 47.89% (gross profit of $54.820 billion), slightly higher than 47.18% in the same period last year, but this figure includes a contribution of about 1 percentage point from tariff refunds. If this factor is excluded, the actual operating performance is not as impressive as the headline data suggests.
A more severe test lies ahead.CFO Kevan Parekh admitted on the call that Apple's previously stockpiled low-priced component inventory is rapidly being depleted, forcing it to purchase memory chips at higher prices. Looking at Apple's balance sheet, this cost pressure has already begun to show — as of the end of the fourth fiscal quarter, the book value of Apple's inventories was as high as $14.541 billion, a surge of 154.30% from $5.718 billion in the same period last year. In addition to stocking up intensively for holiday-season new products, the intake of high-priced memory chips directly pushed up the book amount of ending inventory, and this batch of high-cost inventory will be formally converted into cost of sales in the coming December quarter, thereby directly squeezing profit margins.
Against the backdrop of AI computing centers devouring global DRAM and NAND capacity and driving memory chip prices to continue soaring, even Apple, which has the strongest bargaining power in the supply chain, cannot remain immune. Parekh warned that, dragged down by high memory costs and the cost of launching Siri AI, Apple's gross margin guidance for the upcoming December holiday season (Q1 of fiscal 2027) will plunge to 45% to 46%. This figure is a sharp contraction of 2 to 3 percentage points from this quarter and far below Wall Street expectations.
The second heavy blow is the loss of speed in the high-margin "services engine." As the ballast of Apple's valuation system, the services business had a gross margin of 75.95% this quarter, more than double the gross margin of the hardware business (37.20%). Although fourth-quarter services revenue reached a record high of $31.573 billion, its 9.82% year-over-year growth rate was not only slightly below expectations but also fell below the 10% threshold, marking the lowest growth rate in more than three years. Management even expects services business growth to slow further to 8%-9% next quarter, significantly below the market expectation of 10.7%.
The deceleration of the services business is not a short-term fluctuation but strikes directly at the foundation of the business model.On the one hand, global antitrust regulation is continuing to weaken the App Store's ability to charge high commissions; on the other hand, super apps in the AI era are actively bypassing Apple's "toll booth" — after falling out with Apple over a trade secret dispute, OpenAI (ChatGPT), which originally contributed considerable in-app purchase revenue, has begun directing subscribers to pay on the web. When AI gateways are no longer willing to pay the "toll," the moat of Apple's services ecosystem is bound to be eroded.
The Real Test of the Turnus Era
In the fourth fiscal quarter, Apple's R&D expenses quietly soared 32.30% to $11.730 billion, showing the company's determination to catch up in new foldable form factors, touchscreen Macs, smart home hubs, and Siri AI. However, the all-new Siri AI officially launched this quarter still appears to be faltering in the eyes of the outside world — when competitors' AI Agents can already smoothly execute multi-step complex tasks, Siri's experience remains widely criticized, and its launch costs have instead dragged down the holiday-season margin guidance first.
Over the past four months, Apple, with its restraint in "not participating in the AI arms race" and abundant free cash flow, has won a "safe haven" premium amid Silicon Valley's turmoil and has accordingly returned to the top spot in global market capitalization. But this earnings report also clearly reminds the market thata hardware giant ultimately cannot escape the cost squeeze of the upstream semiconductor memory cycle, and the tax-collection model of a closed ecosystem is also being hit by the AI wave.
For the new leader Turnus, a $5 trillion market capitalization is not a victory banquet but a rigorous test — if he cannot use truly dominant hardware innovation and a better AI experience to digest the lofty valuation, then relying solely on shrewd supply chain allocation and financial buybacks, the storms this "safe haven" can withstand will ultimately be limited.