Author: Jae, PANews
In just two trading days, US stock players experienced a rapid roller coaster ride.
On November 5, US stocks suffered the strongest single-day sell-off in nearly 19 months, with the AI industry chain leading the sell-off. Rumors of "hedge funds collectively blowing up" also quickly fermented on social media, as if a financial storm was imminent.
Unexpectedly, the reversal came so quickly. On November 6, chip stocks took the lead in sounding the horn of counterattack: the Philadelphia Semiconductor Index closed up 4.2%, AMD surged 11%, and AI concept stocks such as Nvidia recovered simultaneously; the Nasdaq closed up 1.1%, and the S&P 500 rose slightly by 0.3%.
This unexpected market movement may have been foreshadowed a month ago. At the same time, a cross-asset capital migration is also quietly unfolding.
Deleveraging selling pressure slows, medium- and long-term risks unresolved
The rebound on November 6 actually showed signs in the last ten minutes of Thursday's close.
Vanda Research data shows that US retail investors clearly turned to buying near the close the previous day, with net purchases exceeding $100 million in the last 10 minutes.
The more critical variable comes from leveraged ETFs. According to Nomura Securities estimates, to complete the net value rebalancing on November 5, leveraged ETFs needed to concentrate selling about $47 billion in stock exposure before the close. This is the second-largest single-day sell-off since statistics began in 2006.
When this massive passive selling was completed before the close, the market's short-term selling pressure was also significantly released. The combined forces of bargain-hunting funds, short covering, and institutional portfolio rebalancing jointly drove price repair. JPMorgan noted in its after-hours commentary that Thursday's intense deleveraging activity cleared out some crowded trades, making the market's positioning structure healthier.
In other words, last night's rebound was more of a technical repair at the short-term trading level. Medium- and long-term contradictions such as a shift in policy expectations and doubts about the return on AI capital expenditure have not truly been resolved.
Blow-up narrative exaggerated, hedge funds deleveraged a month in advance
In this round of US stock turmoil, hedge funds once became the focus of market attention.
According to a Bloomberg report on November 5, Tiger Global's flagship hedge fund lost about 8.5% in October, with year-to-date returns basically flat; Walleye Capital fell about 5.9% during the same period, with year-to-date losses reaching about 6.8%; Lone Pine Capital lost about 8.8% in a single month.
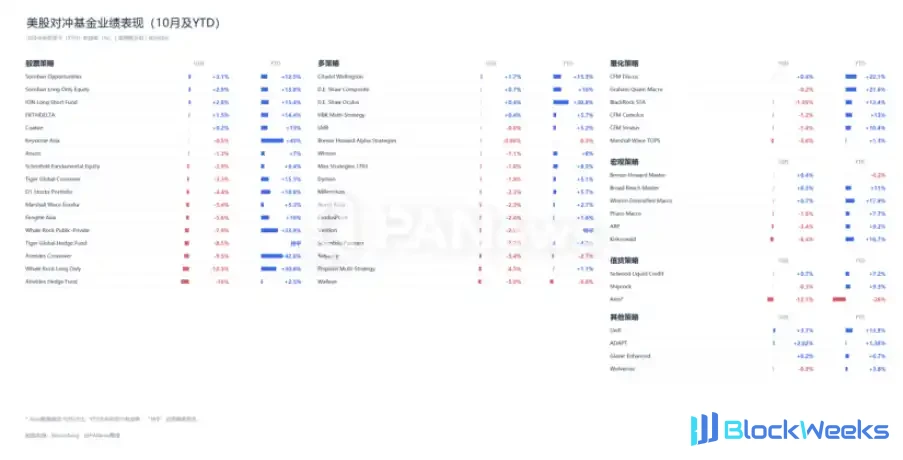
Social media was subsequently filled with panicked narratives of "Wall Street hedge funds collectively blowing up." Hedge funds such as Walleye Capital, Engineers Gate, and Samlyn Capital successively spread news of team cuts, strategy streamlining, and returning capital to investors, intensifying market concerns about a chain of institutional liquidations.
However, business contraction does not equal a blow-up and liquidation; it is more about managers actively controlling risk and adjusting their business models, rather than insolvency-style bankruptcy liquidation.
There is a timeline that is easily overlooked by the market: hedge funds' position reduction and deleveraging had already begun in October, and the crash on November 5 was more likely a concentrated realization of this process.
Goldman Sachs Prime Brokerage data shows that in October, global fundamental equity long/short funds lost an average of about 3.5%, and systematic long/short strategy funds lost about 3.6%. This is the first time since Goldman Sachs began tracking in 2016 that both strategy types posted losses exceeding 3% in the same month.
The more hidden moves occurred in mid-October. In just two weeks, Goldman Sachs' hedge fund clients net sold $20 billion in tech stocks; in the five trading days from October 8 to 14 alone, they wiped out all the net long AI stock positions accumulated since the beginning of 2025. As of the end of October, hedge funds' net leverage ratio fell to 73.4%, down 4.2 percentage points in a single month, the largest monthly decline since March this year.
Morgan Stanley data also reveals this change. Stock-picking hedge funds experienced their largest active position reduction in more than a decade in October, with market exposure cumulatively falling about 9% since June. By the end of October, more than 40% of relevant funds had flat or negative year-to-date returns.
However, hedge fund performance also showed significant divergence, and it was not an industry-wide loss.
Coatue Management recorded a positive return of 0.2% in October, Citadel rose 1.7%, and Quantedge gained as much as 7.2% in a single month.
Some stepped into pitfalls in crowded trades, while others made money in market volatility.
Capital has not disappeared, it has just changed places
Behind the evaporation of trillions of dollars in US stock market value is a massive capital migration.
Money does not disappear out of thin air; it merely flows out of high-volatility, high-leverage tech stocks and into safer, more liquid assets.
The first major destination is US Treasuries. On the day of Thursday's US stock crash, the 10-year US Treasury yield once fell back to 4.84%, hitting a new low since September. Prices and yields move inversely, meaning a large amount of capital is flowing into the bond market.
The second stop is the US dollar. FxPro Chief Market Strategist Alex Kuptsikevich pointed out that the tech stock panic dragged down risk appetite, and the US dollar regained support from a large amount of safe-haven buying.
ING Global Head of Markets Chris Turner also believes that investors are currently more willing to temporarily keep cash in US dollar assets, and the market is closer to shifting into US dollar cash rather than fleeing the dollar.
Just as the US dollar was in favor, the Korean won and New Taiwan dollar, which had been wrongly hit by risk sentiment, also regained attention.
Yesterday, Claudio Piron, Head of Asia FX and Rates Strategy at BofA Global Research, pointed out that the New Taiwan dollar and Korean won also presented buying opportunities after the AI stock sell-off. The sizable current account surpluses of China's Taiwan region and South Korea will provide "strong support" for investors to establish long positions.
Another key judgment from BofA is that AI industry chain companies already have the aforementioned large capital expenditures and export orders, and will not cancel them just because US stocks fall. Continued export settlement over the next 6 to 12 months will form new underlying support for the New Taiwan dollar and Korean won.
Selling climax pauses for now, position clearing may not be over
A rapid rebound after a crash is not uncommon; the real difficulty lies in distinguishing: is it the end of the decline, or a phased recovery?
History does not repeat details, but it always rhymes with similar patterns.
August 2007: Quantitative fund deleveraging
From August 6 to 9, 2007, multiple equity long/short quantitative funds suffered concentrated losses, and the market was bloodied.
Research by MIT scholars Amir Khandani and Andrew Lo found that concentrated liquidation of crowded trades and the temporary retreat of market-making capital jointly led to the abnormal liquidity at that time.
The most severe stage of the sharp decline was concentrated in only 4 days, and some strategies began to rebound after August 10, but the entire deleveraging process lasted from July all the way to the end of the year.
The sharp decline was only the prelude; the real position clearing and risk appetite recovery may take months to unfold.
March 2020: Pandemic triggers broad risk asset sell-off
From February 19 to March 23, 2020, the S&P 500 cumulatively fell about 34%, and the correction lasted more than a month, interspersed with multiple violent single-day rebounds, and it did not regain its lost ground until August of that year.
In the short term, the movement of U.S. stocks over the past two days is closer to the first scenario: the most intense concentrated selling may already be over, but market-wide position rebalancing and the repair of risk appetite are far from finished.
The market's divergence lies precisely here.
Well-known investor Jason Calacanis said that a market bottom may have already appeared, but tech stock valuations could still fall a further 10%, at which point it would be an ideal buying opportunity.
Optimist Tom Lee, chairman of Bitmine, believes that Thursday's U.S. stock plunge was like an aftershock of a "blue tsunami" triggered by midterm election results, and was a combined version of "last year's tariff shock + the DeepSeek moment + this June's Situtational Awareness forced liquidation." Such concentrated selling often bottoms out within a few days and creates buying opportunities.
U.S. stock analyst Mark Minervini offered a more cautious judgment. He believes the decline in U.S. stocks may not necessarily reach the magnitude of the 1987 crash, but could lay the foundation for some form of stock market crash, which could last one to two weeks. If the decline intensifies, the worst case for SPY is a 10%-15% drop from its high. The Nasdaq may fall 20-25%, entering a cyclical bear market similar to 1998.
For now, last night's gain in U.S. stocks is far from enough to offset the previous day's decline. After an asset falls 20%, it needs to rise 25% to return to its original level.
And the Nasdaq, which fell 5.52% on Thursday, even after rising 1.1% the next day, still has a clear gap from its previous position.
After two trading days of violent swings, U.S. stocks stand at a crossroads. The entire narrative that drove AI tech stocks higher over the past few months is now facing a severe reality test. The short-term deleveraging may be coming to an end, but the medium-term game behind issues such as the implementation of industrial policy and the return on AI investment has only just entered deep waters.