The Democratic Party's landslide victory in the U.S. midterm elections has brought a series of overseas "imported risks" to the ground, and the logic of global asset pricing is quietly shifting.
The team of Cao Liulong at Western Securities believes that after the midterm results landed, market concerns about the pace of U.S. AI data center (AIDC) construction being hindered have intensified, and combined with expectations of easing U.S.-Iran relations, U.S. Treasury yields and the dollar have weakened in tandem. The Democratic Party's winning agenda—ending the U.S.-Iran conflict and delaying AIDC construction—all point to a medium-term weak-dollar trend, and the expiration of the year-end temporary funding and the debt ceiling game in early next year further reinforce this window.
Behind the expectation of a slowdown in overseas AI lies a deeper conflict of interest distribution among tech companies, the public, and the government, a structural problem that is difficult to resolve in the short term. In contrast, domestic big tech companies have a lower capital expenditure base and significantly better financing costs, and the Chinese and U.S. AI industries are quietly opening a narrative window of "the East rising and the West falling." The Western Securities research report accordingly maintains its strategic bullish view on Hong Kong internet stocks.
Midterms land, "imported risks" begin to materialize
After the Democratic Party's landslide victory in the U.S. midterm elections, the overseas imported risks previously warned about by the market have begun to gradually play out. The U.S. market is worried that the pace of AIDC construction will be hindered, while expectations of easing U.S.-Iran relations are heating up, driving U.S. Treasury yields and the dollar under simultaneous pressure.
The landing of the elections does not mean that overseas volatility will subside. After winning, the Democratic Party emphasized a key review of data center projects; the whole process is still at the stage of sentiment fermentation, and there may still be back-and-forth in the future. Considering that we are still in a rate-hiking cycle, overseas market volatility should not be underestimated.
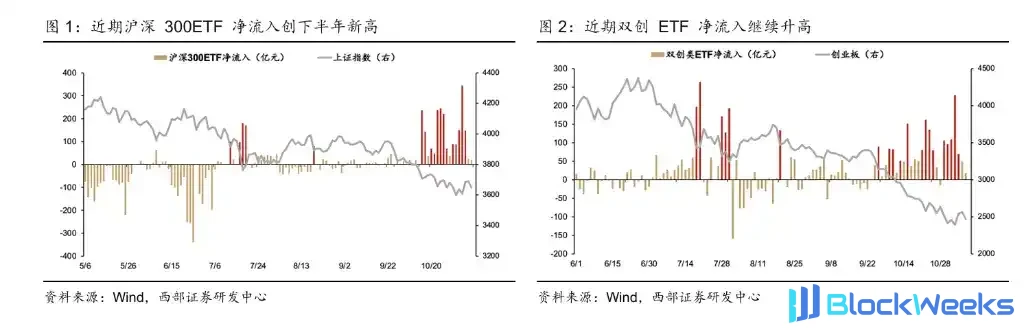
For A-shares, external imported risks remain, but the bottom area is gradually becoming clearer. Policy support has clearly increased—on November 6, Premier Li Qiang of the State Council presided over an executive meeting of the State Council, explicitly requiring "improving the capital market's market-stabilizing mechanism, enhancing the internal stability of the stock market, and promoting the stable and healthy development of the capital market"; the "Report of the State Council on Financial Work," submitted to the Standing Committee of the National People's Congress for deliberation on November 3, also reiterated the relevant statements. At the same time, broad-based ETFs have continued to see high-intensity net inflows, forming bottom support—major broad-based ETFs have seen net inflows for 25 consecutive trading days from September 28 to November 6, with a cumulative scale of more than 414.9 billion yuan based on the CSI 300 and dual-innovation ETF caliber, and the average daily net inflow of CSI 300 ETFs has recently hit a new half-year high.
Democratic victory reinforces the medium-term weak-dollar trend
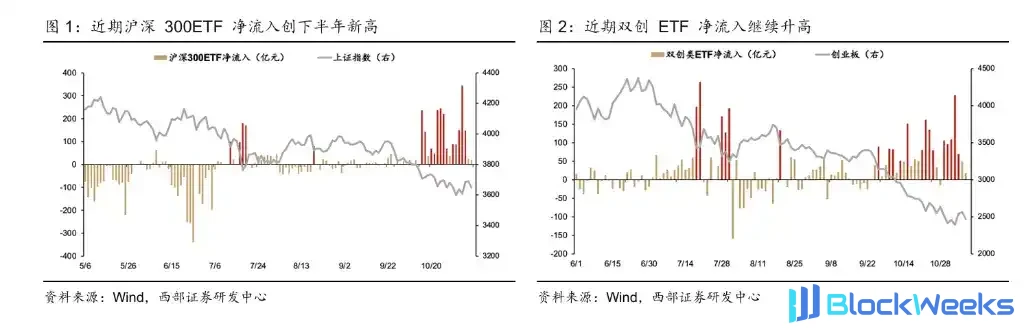
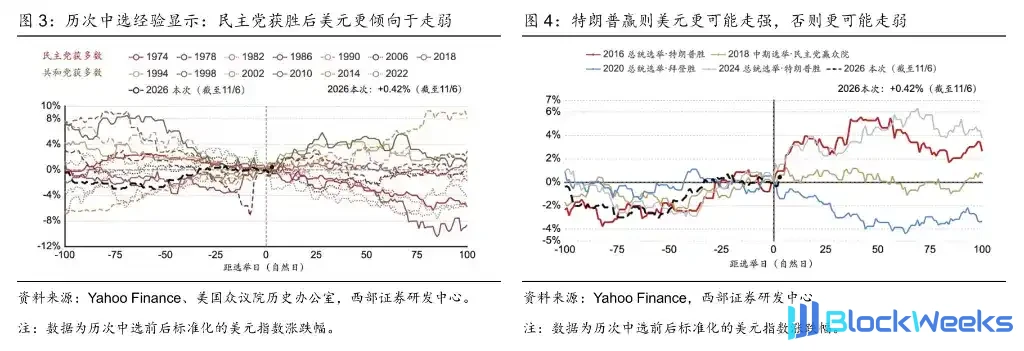
Beyond short-term market fluctuations, what deserves more attention is the medium-term trend. Historical experience shows that after the Democratic Party wins midterm elections, the dollar tends to weaken relatively; after the Republican Party wins, the dollar tends to strengthen. The results of several past elections related to Trump's governance or candidacy also confirm this pattern.
There is also support at the logical level. The core issues supporting the Democratic Party's victory—ending the U.S.-Iran conflict and delaying AIDC construction—all constitute downward pull factors for the dollar, and oil prices have recently begun to reflect expectations of geopolitical cooling. At the same time, the Democratic Party is more inclined to increase spending on welfare areas such as healthcare and education, which will further increase fiscal pressure and trigger market concerns about the sustainability of U.S. fiscal policy.
In terms of timing, the expiration of temporary funding on December 11 and the government debt ceiling issue expected around the first quarter of 2027 deserve key attention. The debt ceiling issue will most likely ultimately be resolved, but the process of tug-of-war between the two parties may create a trading window for a "weak dollar."
AIDC construction slowdown: votes on the surface, taxes underneath
In this round of expected slowdown in AI data center construction, public dissatisfaction is only a surface phenomenon; the deeper contradiction lies in the imbalance in the structure of fiscal interest distribution.
The share of U.S. corporate pre-tax profits in GDP has hit a record high, yet corporate income tax revenue has fallen rapidly from its previous peak to about $380 billion, clearly below the Congressional Budget Office (CBO)'s forecast path at the beginning of the year. The one-time pre-tax deduction policy available for data center investment is one of the important reasons for this gap—the more companies spend in the current period, the less taxable profit there is, and the government's actual tax revenue is accordingly under pressure. In other words, the benefits of AI infrastructure construction are captured by large tech companies, while the social costs and tax losses are borne jointly by the public and the government.

The Democratic Party uses the midterm elections as an entry point, and its core logic is to complete a redistribution of interests rather than to end AI construction itself. In the short term, this change will most likely create rhythmic disruptions to the pace of data center construction. This trend is already visible: the proportion of data center-related restrictive bills in 2026 has clearly risen. There are three key observation points going forward: the ERCOT report to be released on December 10, 2026, relevant legislative developments after the state legislature opens on January 12, 2027, and administrative measures after the new governor takes office on January 19.
Chinese and U.S. AI usher in a narrative window of "the East rising and the West falling"
The slowdown doubts facing overseas AI objectively provide domestic AI with an opportunity to retell the narrative of "the East rising and the West falling," with the core differences lying in two dimensions: capital expenditure pressure and financing costs.
At the capital expenditure level, the absolute base of domestic big tech companies is significantly lower than that of overseas cloud companies, and the pressure of slowdown is relatively smaller. Data shows that in 2026, U.S. cloud companies' capital expenditure generally exceeds operating cash flow, and the situation is expected to deteriorate further in 2027; while domestic cloud companies are expected to see improvement in 2027.

At the level of financing costs, the gap between Chinese and American cloud providers is particularly stark. Leading Chinese cloud provider groups rely mainly on RMB financing, with significantly lower costs—taking Alibaba as an example, as of March 2026, the weighted average interest rates on its RMB-denominated short-term and long-term bank borrowings were only 1.5% and 2.5%, respectively. In contrast, overseas, high-interest USD debt has become an important constraint on AIDC expansion: Oracle's newly issued bonds in November 2026 carried coupons as high as 7% to 8.65%, while CoreWeave's ordinary bonds carried coupons in the range of 8.5% to 9.75%.

This structural difference makes the domestic AI industry chain relatively more resilient to risk, with more stable growth expectations.
Strategic allocation window: maintain bullish view on Hong Kong internet stocks
The Western Securities report argues that while overseas imported risks disrupt global risk appetite, they also open a narrative window for domestic "overtaking on the curve"; the time window of a phased weakening of the US dollar after the election provides a strategic opportunity to increase allocation to Hong Kong internet stocks.
The report organizes allocation around three main lines:
Real estate and consumption: If overseas liquidity reaches a turning point and the external environment improves, a series of domestic fiscal policies are expected to be implemented at an accelerated pace, supporting housing prices and repairing household sector balance sheets. The report believes that at that time some real estate stocks may have room for recovery of twofold or more, and the consumer sector is expected to move toward a "consumer core assets bull market."
Hong Kong internet stocks: If an overseas liquidity shock occurs, Hong Kong stocks may adjust significantly accordingly; if overseas liquidity reaches a turning point, Hong Kong stocks are expected to usher in a valuation re-rating—after the Federal Reserve launched QE in March 2020, Hong Kong stocks subsequently rose by more than 170%. The domestic computing power chain under the background of self-reliance and controllability is also expected to recover in tandem.
Gold and non-ferrous metals: If an overseas liquidity shock materializes, gold and non-ferrous metals will come under phased pressure; if a liquidity turning point appears, the "commodity super cycle" narrative is expected to return.
Markets carry risks, and investment requires caution. This article does not constitute personal investment advice, nor does it take into account the special investment objectives, financial situation, or needs of individual users. Users should consider whether any opinions, views, or conclusions in this article are suitable for their particular circumstances. Investment based on this is at one's own risk.