Author | Huang Yida
Editor | Zhang Fan
On November 12, Nvidia suddenly announced that company co-founder Jensen Huang has resigned from the positions of president, chief executive officer, and director, effective immediately. Current Chief Financial Officer Colette Kress will serve as interim CEO, and the board of directors has simultaneously appointed Harvey Jones as the company's first chairman in its history and initiated the process of selecting a new CEO.
Since founding Nvidia in 1993, Jensen Huang's 33-year tenure at the helm has officially come to an end. From GPUs to artificial intelligence, Jensen Huang led Nvidia through several major strategic transformations, turning a startup chip company into one of the most influential technology giants in the world.
However, less than five months ago, Jensen Huang still received about 99% of the votes in favor in the director election at Nvidia's annual shareholders meeting. Such a stark contrast before and after has also prompted the market to re-examine a corporate governance issue that has long been obscured by Nvidia's dazzling performance:
As the company's founder and long-term leader, why did Jensen Huang not, like Google's Page and Brin or Meta's Zuckerberg, consolidate his own control through a dual-class share structure?
01 1999 Was Not Yet the Era of Dual-Class Shares
The answer to this question may need to start with the equity arrangements when Nvidia went public in 1999. At that time, it was common for Silicon Valley technology companies to go public with "one share, one vote" arrangements. For founders, they could influence company decisions through shareholding, executive positions, personal reputation, and other aspects, but they did not have voting rights naturally superior to those of ordinary shareholders. Nvidia also followed this tradition and issued only common stock.
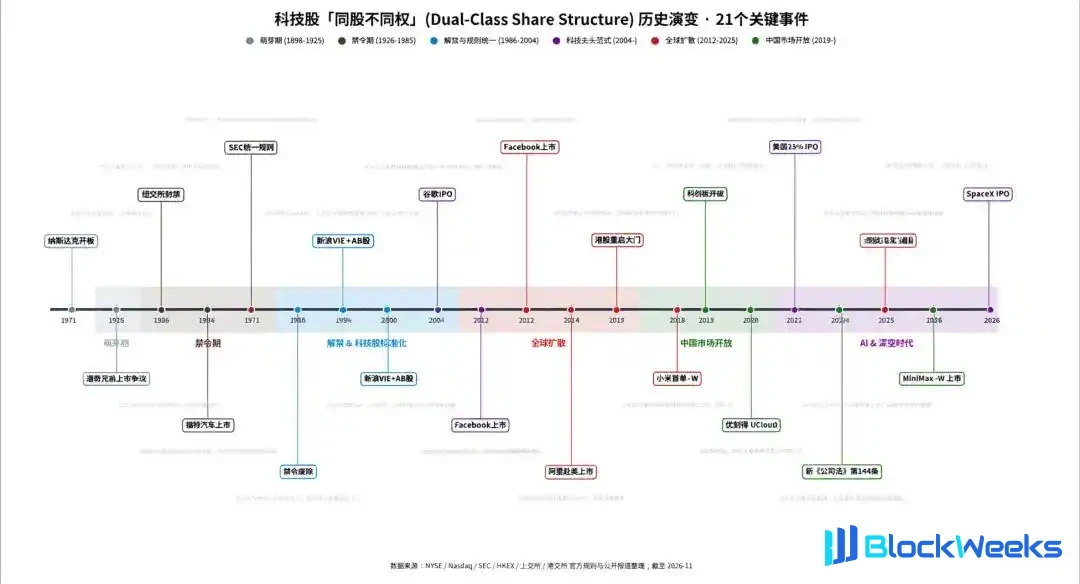
As for the dual-class share structure, it was actually not an invention of the internet era either. As early as the last century, many well-known U.S.-listed companies used dual-class share structures to maintain control through shares with different voting rights, typical examples being Ford Motor and The New York Times. However, explicitly using this system to protect the long-term strategy of technology companies and gradually making it a commonly adopted equity structure for large technology internet companies' IPOs was a trend that formed only later in the internet era.
In 2004, Google adopted an AB share structure when it went public. At the voting rights level, Page and Brin set the Class A shares held by the public at one vote per share and the Class B shares held by founders and others at ten votes per share. Google's prospectus explicitly stated that a traditional public company structure might weaken the independence of the enterprise, and therefore it hoped to use AB shares to maintain management's long-term control over the company and safeguard the implementation of long-term strategy.
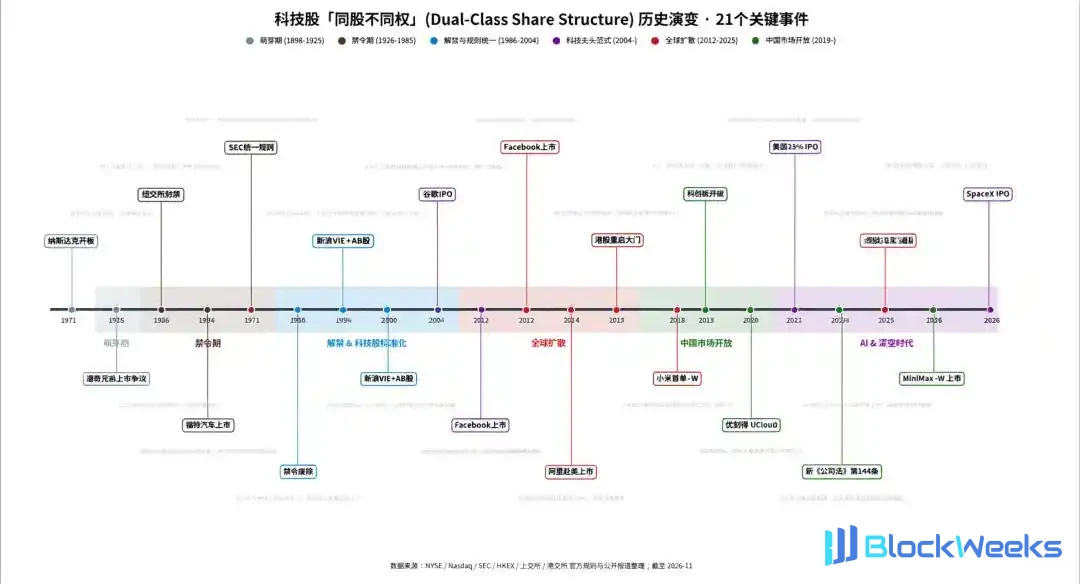
Figure: Historical evolution of dual-class share structures among technology stocks; Source: 36Kr Graphic
By comparison, Nvidia went public only five years earlier. Its continued use of a one-share, one-vote equity arrangement largely reflected the equity governance conventions of technology companies at that time. Moreover, Nasdaq Rule 5640 restricts listed companies from unfairly weakening the voting rights of existing ordinary shareholders after the fact through methods such as issuing super-voting shares. Therefore, for Nvidia, which was already listed, the institutional difficulty of introducing super-voting rights to protect the founder was already far higher than before the IPO.
02 Jensen Huang's Shareholding Has Been Continuously Diluted
Nvidia's equity ownership is quite dispersed, and this was already evident from the time of its listing. Its 1999 prospectus disclosed that Jensen Huang held about 13.1% of the shares before the IPO, which fell to 10.8% after the IPO; by 2026, his shareholding ratio had further dropped to 3.58%. Financing, additional share issuances, equity incentives, and changes in personal shareholding caused Jensen Huang's shareholding ratio to continue declining, and his voting rights correspondingly continued to weaken, laying the groundwork for this "ouster incident."

Figure: Timeline of Jensen Huang's equity dilution; Source: 36Kr Graphic
In the early years, there had already been precedents of Silicon Valley technology company founders losing control due to equity dilution. In 1985, Jobs and Apple CEO Sculley clashed fiercely over the company's operations. Although Jobs was still Apple's largest individual shareholder at the time, his shareholding ratio had fallen to about 11%, no longer enough to sway the board's decisions. The board chose to support Sculley, and through business structure adjustments, Jobs was relieved of his management authority and left the Apple he had founded in September of that year.
Looking at Microsoft, after its 1986 listing, Gates still held about 45% of the shares. Although his personal shareholding ratio gradually declined, he still retained about 14% of the shares before stepping down as CEO in 2000. Thanks to Gates's relatively high shareholding ratio in the early period after listing, the relatively gradual process of equity dilution thereafter, and the leadership authority accumulated over the long term, Gates always maintained strong control over the company during his tenure as CEO.
By comparison, Jensen Huang held only about 11% of the shares when Nvidia went public. Compared with Gates, the voting rights corresponding to the shareholding ratio of the "leather-jacket war god" were clearly weaker. Moreover, as his shareholding ratio further declined thereafter, Jensen Huang's already weak voting rights continued to diminish, so it can be said that he lost early on the foundation for dominating company decisions through controlling ownership.
03 Jensen Huang Led the Company for 33 Years Relying on Performance Authority
Therefore, Jensen Huang's influence over Nvidia is difficult to explain by the voting rights corresponding to his equity ratio. Management authority in corporate operations never comes only from the ballot box; it also comes from performance authority, strategic judgment, and the board's long-term trust in executives.
From graphics chips to programmable GPUs, and then to continuous investment in the CUDA ecosystem, Nvidia repeatedly bet on long-term technology roadmaps before the market reached consensus. CUDA in particular was difficult to immediately deliver substantial returns in the early days, yet it gradually built up a competitive moat based on software-hardware synergy; afterward, generative AI drove an explosion in computing power demand, and Nvidia further evolved from a chip supplier into a core participant in global AI infrastructure.
These key strategic decisions and the enormous commercial success they brought gradually established Jensen Huang's core leadership position at Nvidia. In the company's daily operations, Jensen Huang long dominated product R&D direction, R&D resource allocation, supply chain coordination, and customer relationship management. The company's flat management style strengthened his influence over frontline business and experiential decision-making. For the board and institutional investors, supporting him was both an recognition of past achievements and an inclusion of trust in his ability to judge the future.

Figure: Nvidia's long-term operating revenue performance; Source: wind, 36Kr
Therefore, even though Jensen Huang did not have absolute control in the legal sense, he long possessed de facto strategic dominance. Relying on continuously delivered performance, he maintained his leadership position for 33 years without equity protection. In the director election in June 2026, he received about 99% of the votes in favor, which is an intuitive manifestation of this trust.
But the above "Jensen Huang model" has an inherent condition: performance authority must be continuously recognized. It can strengthen as the company succeeds, but once operating performance or personal reputation is hit, the leadership authority accumulated over the long term may quickly weaken. In particular, Jensen Huang, lacking absolute control, may therefore lose the board's support and even lose operational dominance over the company. This "ouster incident" is clear evidence of the above view.
04 What Exactly Does AB Share Protect?
Based on Nvidia's board-centered governance model, according to the company's bylaws, the board only needs the support of a majority of directors to have the authority to appoint or remove senior management personnel such as the CEO at any time, regardless of whether there is just cause. Even as the founder, Jensen Huang cannot unilaterally veto the board's personnel decisions based on his less than 4% shareholding.
For Jensen Huang, who holds a relatively low shareholding percentage and lacks absolute control, even as a long-serving CEO, he must rely on performance growth and shareholder trust to maintain his leadership position. Since he cannot control the board through his own voting rights, the board can form a substantive check on his power and promote management personnel adjustments when necessary. Thus, Jensen Huang's resignation this time is not surprising; it is precisely the result of the combined effect of Nvidia's long-standing equity structure and corporate governance mechanism.
Jeffrey Sonnenfeld, a professor at Yale University, pointed out in a recent interview that Jensen Huang successfully led Nvidia for more than 30 years without the protection of dual-class shares, becoming a powerful example against the AB share system; however, ironically, if Nvidia had granted him super voting rights back then, it would now be much more difficult to remove him.
Google and Meta are typical AB share structures, where super voting rights give founders stronger corporate control, enabling them to reduce interference from short-term market fluctuations and shareholder pressure and to promote long-term strategic planning. But when a founder's judgment or behavior encounters problems, ordinary shareholders may find it difficult to change the corporate governance landscape through voting. Therefore, AB shares amplify the founder's strategic autonomy while correspondingly reducing the convenience of external error correction.
Nvidia did not adopt an AB share structure, which is due both to historical factors at the time of its 1999 listing and to a governance logic different from that of tech giants such as Google and Meta, namely choosing to speak through performance rather than locking down control through institutional arrangements, thereby retaining the board's supervisory and error-correcting capabilities. Jensen Huang's resignation this time once again proves that no matter how great the authority of past performance may have been, a founder lacking institutional control will always be constrained by corporate governance rules.
The content of this article represents only the author's views.
Markets carry risks, and investment requires caution. Under no circumstances do the information or opinions expressed in this article constitute investment advice to anyone. Before making investment decisions, investors should, if necessary, consult professionals and make prudent decisions. We do not intend to provide underwriting services to any trading parties or any services that require specific qualifications or licenses to engage in.