
Author: Zhou, ChainCatcher
On October 26, according to Bloomberg citing people familiar with the matter, Hong Kong-based crypto payment card company RedotPay is considering confidentially filing for a U.S. IPO before the end of the year, targeting a valuation of at least $5 billion. At the same time, the company is still in talks with investors for a Pre-IPO funding round at a valuation of $4 billion to $5 billion.
In August of this year, Bloomberg reported that RedotPay postponed its listing plans due to regulatory and legal issues, and the company subsequently raised objections. In the same month, a Binance-affiliated entity sued its three co-founders in Hong Kong, seeking about $470 million in damages, and the case has not yet been ruled on.
From surpassing a $1 billion valuation in September last year to now aiming for $5 billion, this company, founded only three years ago, has seen its valuation increase about fivefold in just over a year. Can its growth and compliance foundation support this price?
Valuation Quintupled in a Year, $5 Billion Is a Bit Expensive
RedotPay was founded in 2023, and its core business is to let users deposit stablecoins such as USDT and USDC into their accounts, then spend through its Visa card at merchants worldwide, with the system automatically completing the conversion from crypto assets to fiat currency at the time of payment.
In September 2025, RedotPay completed a $47 million funding round, with its valuation surpassing $1 billion; in December, it completed a $107 million Series B led by Goodwater Capital. In February of this year, Bloomberg first reported its plan to list in the U.S., targeting a valuation of more than $4 billion.
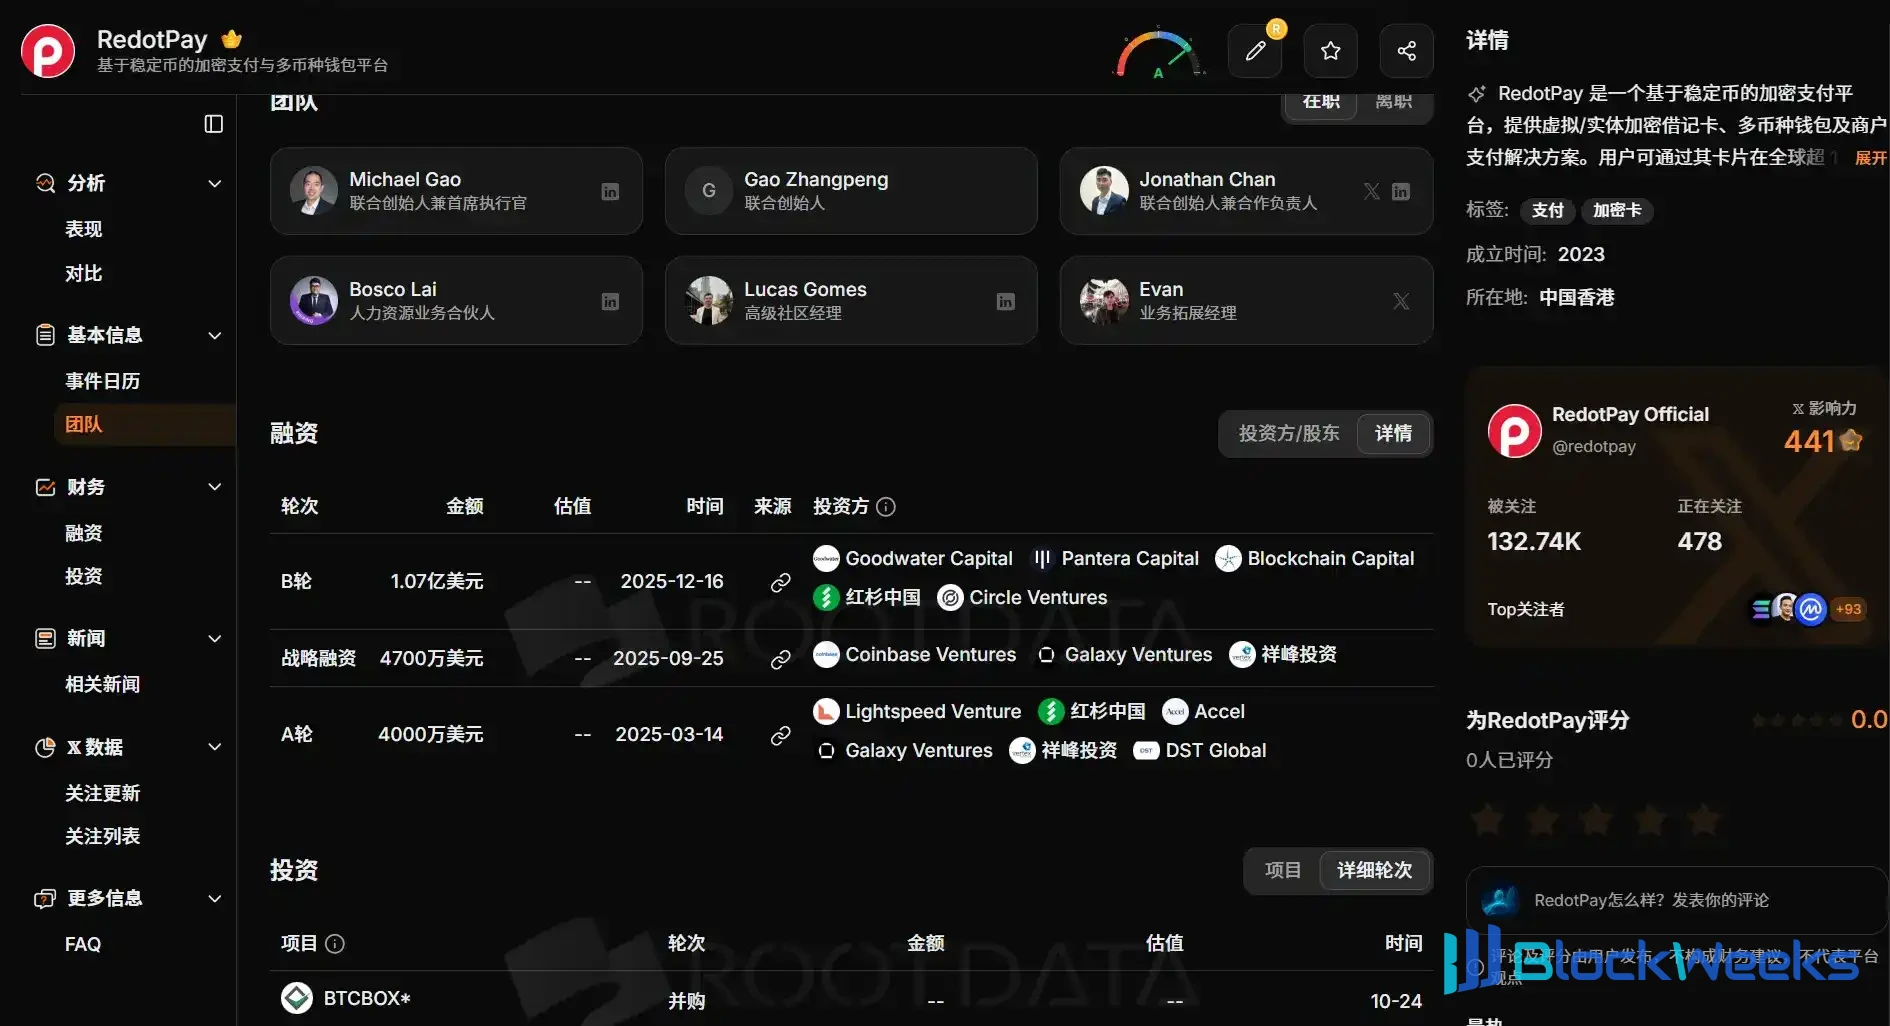
Image source:RootData
The latest report shows that JPMorgan, Goldman Sachs, Jefferies, and Barclays are involved in its listing work, with Barclays' participation previously undisclosed.
What supports this valuation is a set of impressive operating figures. According toBloomberg citing people familiar with the matter, RedotPay currently has more than 9 million customers, annualized revenue of more than $180 million, an operating margin of more than 50%, and revenue in the first three quarters of this year grew by more than 50% year over year.
At a valuation of $5 billion, RedotPay's valuation is about 28 times its annualized revenue. Roughly converted based on the operating margin, the corresponding operating profit multiple is about 55 times, while the listed stablecoin issuer Circle's price-to-earnings ratio as of late October was about 50 times.
The impressive year-over-year growth rate largely comes from last year's low base. Data from crypto card data platform Paymentscan shows that RedotPay's card spending in the first three quarters of this year was about $3.08 billion, an increase of about 64% from $1.87 billion in the same period last year. In the first half of last year, its monthly spending was still between $140 million and $220 million.

It should be noted that RedotPay's card spending data on Paymentscan is self-reported by the company, while top-up data comes from on-chain tracking.
Looking at recent months, both sets of data show that growth has stalled. In September, RedotPay's on-chain top-ups were $537.9 million, basically flat compared with $534.4 million in August; card spending was $403.2 million, compared with $403.6 million in August.
Over the same period, competitors are still accelerating. The Paymentscan leaderboard shows that RedotPay's spending over the past 90 days grew by 12.9%, while EtherFi and KAST grew by 42.5% and 35.5%, respectively.

Revenue growth has also not kept up with capital inflows. From November last year to August this year, RedotPay's monthly top-up amount grew by 68.4%, while the company's disclosed annualized revenue only increased from $150 million to $180 million, an increase of about 20%; during this period, it also raised foreign currency transaction fees and ATM withdrawal fees. Whether the gap between the two comes from a decline in unit revenue or changes in non-card business cannot be determined from currently public information.
The track is expanding, but RedotPay's moat is getting shallower
In contrast to RedotPay's slowdown, the entire stablecoin card track is still expanding rapidly. Paymentscan data shows that in July this year, monthly crypto card spending exceeded $1 billion for the first time, about three times the year-earlier level, and further rose to about $1.23 billion in September.
As the market grows, RedotPay's relative position is declining. Among the roughly 30 card projects tracked by Paymentscan, RedotPay's share of spending once exceeded 90% in 2024, and fell back to about 33% in September this year. During this period, its own spending was still growing; the change in share mainly came from the rapid scaling of later entrants such as EtherFi, KAST, and Plasma One.

The reason later entrants can catch up quickly is related to the lowering of the barrier to card issuance. Infrastructure provider Rain is a principal member of both Visa and Mastercard, provides card issuance services to more than 200 companies, and completed a Series C funding round in January this year at a valuation of $1.95 billion. By connecting to such platforms, brands can launch their own card products in a relatively short period of time.
By comparison, RedotPay's advantages come more from channels. In January this year, ChainCatcher reported in the article "A valuation of $2 billion in three years, how does RedotPay do it?" that RedotPay initially acquired customers through offline distribution networks, promoting in emerging markets such as Nigeria, Brazil, and Southeast Asia with the help of local KOLs, OTC merchants, and community leaders.
What sustains this channel system is relatively high fees and promotional incentives. According to public information, RedotPay's virtual card issuance fee is $10, and the physical card fee is $100. Paymentscan's actual testing shows that the comprehensive markup when spending in foreign currencies is about 2.2% to 2.3%. Referrers can receive a reward of 20% to 40% of the card issuance fee, as well as a share of 0.05% to 0.25% of transaction volume, and second-level referrers can also participate in the distribution.

This means that channel costs have already been written into the business rules. Once fees are pushed down in competition, the room for promotional incentives will also shrink accordingly. The platform also believes that RedotPay is more suitable as a bridge between stablecoins and local payment systems, and that for most users in the United States and Europe, there are often more competitive local options.
In July this year, Swiss payment platform Fiat24 suspended its crypto asset deposit function, and Paris-based startup Kulipa ceased operations due to debt repayment problems, and the card projects of about 20 wallet and fintech companies were interrupted as a result. The rising costs of card issuance, clearing, and compliance are pushing small and medium-sized players out of the market.
Beyond the $470 million lawsuit, RedotPay still has compliance accounts to settle
In late October, RedotPay announced the acquisition of Japanese crypto asset exchange BTCBOX, and acknowledged in the announcement that the company does not have a crypto asset exchange business license in Japan, and that its existing services for Japanese residents do not comply with local regulatory requirements.
Currently, RedotPay has suspended new user registrations in Japan and removed the app from the local app stores, and existing services will be gradually restricted until terminated. The acquired BTCBOX suspended all services in January this year due to a customer information leak and only resumed in phases in August; the transaction amount was not disclosed.
More closely watched isthe lawsuit with Binance. According to a Bloomberg report in August citing Hong Kong court documents, a Binance-affiliated entity accused RedotPay of breaching their cooperation agreement by diverting more than 470,000 users from Binance Card to RedotPay, and is seeking $472.8 million in damages from its three co-founders based on a lifetime value of $925 per user.
The core of the dispute lies in the segregation of funds. An agreement signed by both parties in March 2025 required that funds from Binance Pay must not be used to top up RedotPay cards. Binance said it discovered the breach in March this year and subsequently terminated the cooperation in April.
RedotPay denies the allegations, saying it will vigorously defend itself, and the Hong Kong case has yet to be ruled on. It is reported that over the past year at least five executives have left RedotPay, and its head of legal also left the company in July this year.
On the licensing front, RedotPay did add quite a few this year. In March, it obtained an Argentine VASP license as well as MSB registrations in Canada and the United States; in June it completed a Mexican VASP registration; in August it obtained its first U.S. state-level money transmitter license, with applications pending in more than 20 other states; and in September it obtained lending licenses in two states.
However, these new licenses mainly point to U.S. business that has not yet been launched. RedotPay said in August that its $180 million in annualized revenue and approximately $14 billion in annualized payment volume are both processed through non-U.S. regulated payment processors, and its card products have not yet launched in the United States.
In September, RedotPay announcedthe completion of an anti-money laundering review conducted by a Big Four accounting firm, but the review covered its two Hong Kong-licensed subsidiaries, with the benchmark being the relevant guidelines of the Hong Kong Companies Registry.
On the card issuance side, RedotPay's official website shows that its cards are issued by Singapore's Xfers under a Visa license, with RedotPay operating the card program as program manager. This differs from companies such as Rain that hold principal membership of card organizations, and entails reliance on external institutions.
In addition, ChainCatcher previously noted that RedotPay's interest-earning and lending businesses are in a gray area in terms of legal characterization. Both businesses are still operating, and the interest-earning product has even been included in paid membership benefits, with no definitive regulatory characterization yet.
Overall, RedotPay's year-over-year growth remains impressive, but on-chain top-ups and card spending have both plateaued over the past two months, and revenue growth has clearly slowed relative to capital inflows. Later entrants in the sector are scaling faster, and the rectification of its Japan business and the unresolved litigation also indicate that its compliance structure is still being adjusted.
RedotPay has now completed a financial audit by a Big Four accounting firm. If it submits its application before the end of the year as planned, once the prospectus is made public, disclosures on quarterly revenue, revenue composition, user geographic distribution and litigation risk will become key to testing this valuation.