Just as the global AI computing power sector is being bloodied, semiconductor research firm SemiAnalysis has added another kick.
In its latest model update, it significantly revised down global AI accelerator capital expenditure, shipments, HBM demand, and power demand.
Among them, the adjustments for 2028 to 2030 are the most significant: the 2028 capital expenditure forecast was cut by 28%, and 2029 and 2030 were cut by 41% and 40%, respectively.
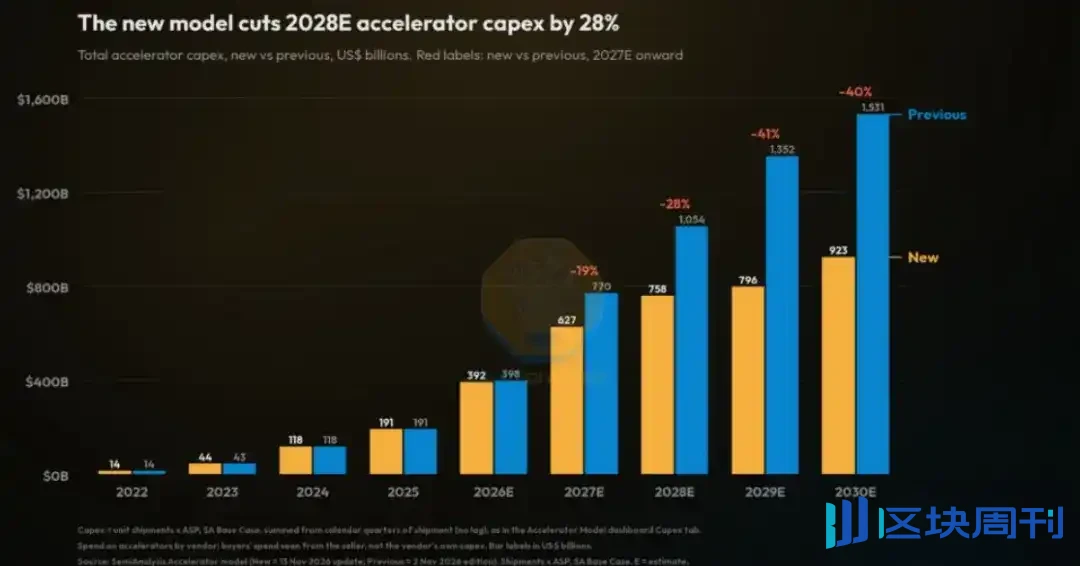
According to the new model estimates, global AI accelerator capital expenditure in 2030 will drop from the previously forecast $1.531 trillion to $923 billion, a decrease of $608 billion.
At the same time, the cumulative forecast for accelerator logic wafer shipment area from 2026 to 2030 was revised down by 17%, with Nvidia accounting for 66% of the reduction.
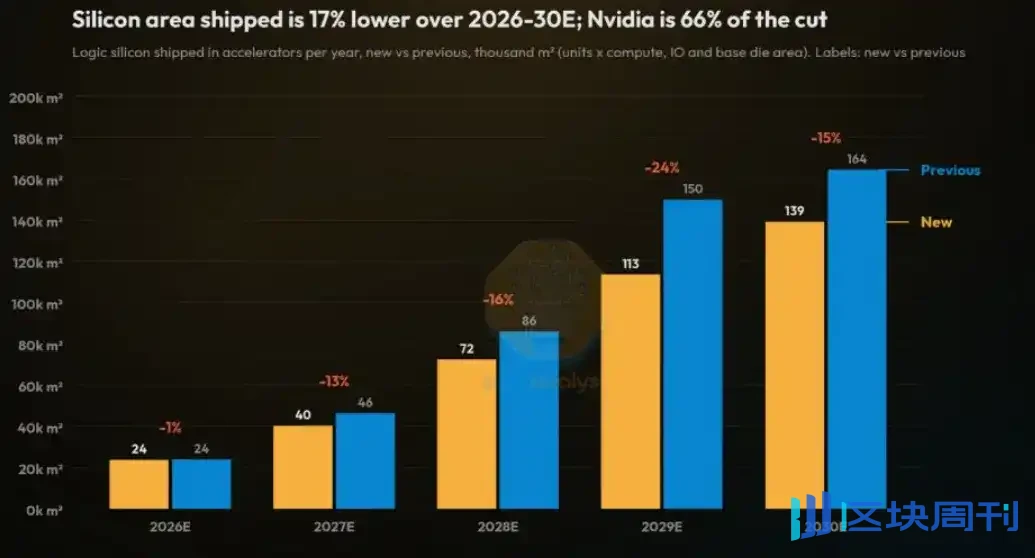
The impact of this set of numbers is first reflected in the breaking of the market's previous narrative of "infinite expansion" of AI infrastructure.
Over the past two years, the capital market generally assumed that cloud vendors and AI labs would continue to add computing power investment at extremely high intensity, thereby driving valuation re-rating across segments such as GPUs, HBM, optical modules, data center power, and liquid cooling.
But SemiAnalysis's revision shows that the 2026 capital expenditure expectation is basically stable, and the real obvious inflection point appears after 2027, especially in 2029 and 2030, when the annual investment scale that originally exceeded $1 trillion has now been revised down to the $800 billion to $900 billion range.
There are three reasons behind the downward revision:
First, AI revenue growth is slowing. The growth rate of new annual recurring revenue at frontier AI labs declined in the third quarter, prompting institutions to reassess whether Token revenue can continue to cover high computing power costs.
Second, the financing environment is tightening. Debt and equity investors are more cautious about projects lacking long-term procurement commitments from cloud service providers, which will affect the development of data center land, power, and building structures.
Third, U.S. regulatory and grid connection constraints have intensified, and 5.8GW of data centers expected to be commissioned between the second half of 2027 and the first half of 2028 will be delayed.
The impact on the industrial chain is not evenly distributed.
Nvidia is hit the hardest. Not only have shipment forecasts been significantly cut, but the average selling price assumptions for the new-generation Feynman series products have also been notably lowered.
For example, the average selling price of Feynman was cut from about $110,000 to about $78,000, and Feynman Ultra from about $175,000 to about $98,000.
This shows that competition in AI chips is shifting from "who has capacity" to "who has higher cost-effectiveness," and alternative platforms such as TPU, Trainium, and AMD GPUs are weakening Nvidia's pricing power.
The simultaneous downward revision of HBM and power demand also deserves attention.
The 2028 global HBM shipment forecast was cut by 30%, and 2030 AI accelerator power demand was cut by 34%.
This does not mean that the memory and power segments lose value, but rather that the industrial chain is shifting from scrambling for capacity and power to allocating capacity according to returns.
HBM still accounts for a relatively high share of the AI accelerator bill of materials, and HBM4, advanced packaging, and customized memory still have structural opportunities; bottlenecks on the power side will not completely disappear either, but the order pace will depend more on the grid connection progress of specific projects.
For the market, this round of downward revision is more like an early de-bubbling calibration.
Previously, the market easily understood AI computing power investment as a one-way upward curve, but in reality it is jointly affected by revenue verification, financing constraints, power grid connection, chip efficiency, and the competitive landscape.
Going forward, key observations include cloud vendors' capital expenditure guidance, accelerator order visibility, changes in HBM contract prices, data center grid connection queue times, and the share of inference workloads in total computing power.
If inference demand continues to grow, unit computing power costs decline, and effective utilization improves, the industrial chain will still receive structural support; if the returns of long-term projects are difficult to verify, capital expenditure forecasts may still be revised further.
At present, the global AI computing power sector is going through a painful stage of valuation downgrades and bubble bursting.
Even so, it is still impossible to determine whether this stage is complete. Although valuations appear to have fallen a lot, the question is whether the forecast parameters in the valuation models have been revised down simultaneously. If not, then valuations may not appear undervalued.
The best approach is still to patiently wait for the market to clear itself.
What can be expected is that market inertia often overshoots. Although there is a lot of bad news and the AI computing power sector has retreated sharply, if the market overcorrects and truly pushes valuations to extreme lows, combined with the clearing out of various leveraged funds and sellers, while short positions are at historical highs, that could instead bring a huge rebound.
As for when this opportunity will come, only the market can give the answer.