Long-accumulated AI bubble worries were suddenly set off by the result of an election.
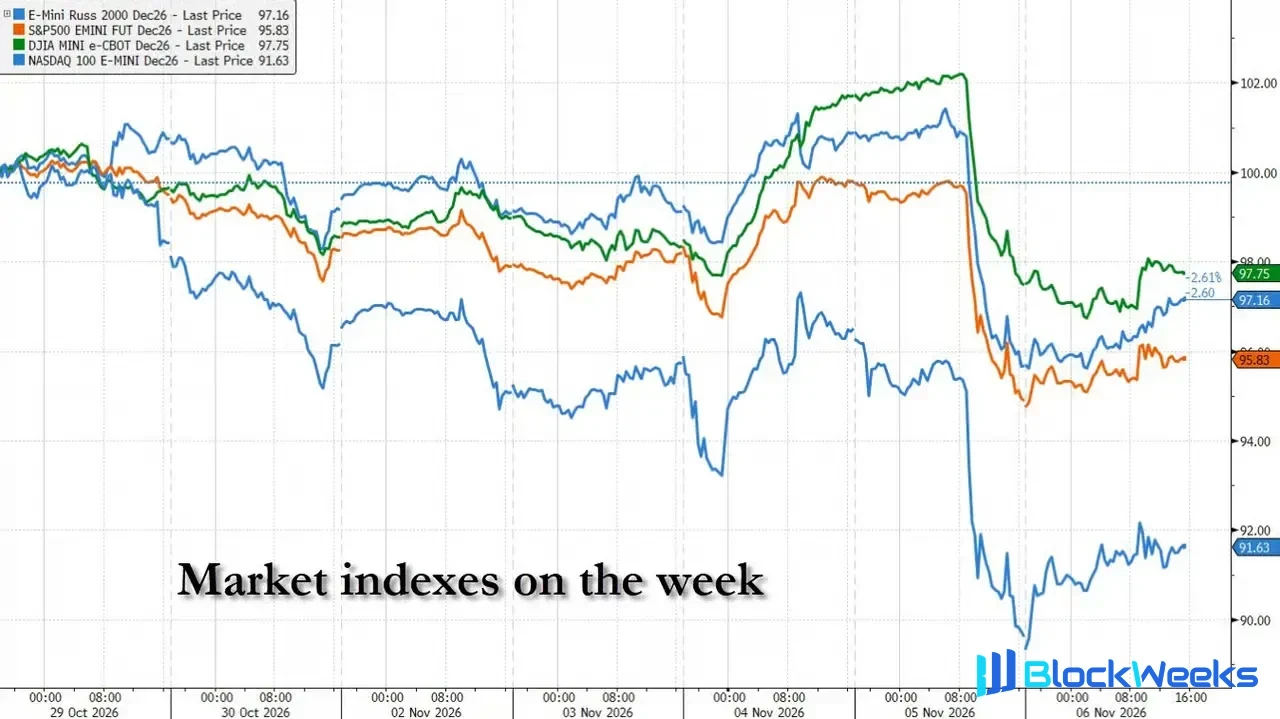
The Democratic landslide victory in the U.S. midterm elections for Congress should have been a signal of "risk clearing"—and the stock market initially reacted that way. But in less than 24 hours, Wall Street completed a dramatic reversal from celebration to panic. On Thursday, the Nasdaq 100 recorded its largest single-day decline since March 2020, wiping out $2.3 trillion in market value in one day; measured from its October 6 high, U.S. stocks have lost a cumulative $5.7 trillion in market value. The VIX fear index surged from 16.6 points to nearly 28 points, one of the most violent volatility events in history starting from the calmest starting point.
The trigger was the market's repricing of the Democratic Party's policy stance—especially the latter's deep skepticism about the large-scale expansion of AI data centers. This political variable, combined with already highly crowded AI trading positions, created a rare scene of retail investors, hedge funds, and quantitative strategies stampeding simultaneously. The reason this selloff was so devastating is that it left almost no one any time to react—from retail investors fleeing first, to hedge funds following, to quantitative strategies mechanically liquidating—all completed within just a few hours.
Election Night: From Celebration to Confusion
On Tuesday night, the Democratic Party's overwhelming victory exceeded expectations. According to The Wall Street Journal, Ben Emons, head of an investment research institution, sat in his Manhattan office from 9 p.m. to midnight as his phone hardly stopped ringing. While taking client calls, he did push-ups beside his desk to stay alert. "People were caught off guard," he said. "This is a real shock event."
At the time, stock index futures initially slipped during the early vote count, but as the Democratic victory became clear and Trump publicly said he accepted the election result, futures quickly turned positive. George Mateyo, chief investment officer at Key Private Bank, watched the live broadcast at home while texting colleagues. His judgment was that the risk of a fierce post-election dispute had dissipated, and the market should rightly welcome that.
That judgment was confirmed on Wednesday morning. Sectors tied to the "real economy," such as construction and retail, rallied strongly, and the Dow recorded its best single-day performance since April. Wall Street briefly breathed a sigh of relief—thinking the election uncertainty had been written off.
However, that rebound soon proved to be a false breakout.
Retail Investors Flee First, Panic Spreads on Social Media
Thursday's selloff was first ignited by retail investors.
In the first half hour after the open, the Nasdaq plunged sharply, and individual investors' net selling hit a historic record. According to data from research firm Vanda Research, Thursday's single-day retail net selling was second only to the two trading days during the March 2020 COVID shock. JPMorgan's market intelligence desk noted that retail selling deviated from normal levels by more than three standard deviations.
"I started working at 7 a.m.," said Raphael Monges, a Columbia University engineering graduate student and member of the Columbia Options and Futures Trading Club. "I saw the market open, the Nasdaq falling fast, then the S&P. The Nasdaq was crazy, all AI stocks were dumping. My phone started vibrating nonstop, everyone was staring at stocks, all red."
San Francisco investor and content creator Kevin Xu glanced at the market at 10:30 a.m. on Thursday and froze. The Nasdaq was already down 4%, and his retirement account had evaporated six figures overnight. "There's nothing you can do," he said. "You can only watch." In his social media feed, other retail investors posted memes, vented in all caps, and some even posted the phone number for a mental health hotline.
Joel Rieger, a 50-year-old retail trader in California, did not adjust his positions during the turmoil. "Yesterday's portfolio took a heavy hit, red everywhere," he said. "It's going to hurt in the short term."
Hedge Funds Follow, Institutional Selling Finds No Buyers
The retail exodus was only the prelude. As the market direction became established, hedge funds and long-only asset managers joined the selling, while almost no buyers appeared on the other side.
According to Bloomberg, "institutional investors have stepped aside, while retail and systematic strategies are selling aggressively," Vanda global macro strategist Viraj Patel wrote in a report. "This kind of flow dynamic is extremely rare outside of genuine periods of market stress."
Ron Adler, co-head of global equities high-touch trading at JPMorgan, witnessed the whole process from the cash trading desk—trading volume that day surged 50% from normal levels. "What we saw was partly portfolio pain and indiscriminate selling," he wrote in a note to clients. "The candor of today's flows was reasonable in direction, but the scale was staggering."

According to estimates from Goldman Sachs' Prime Brokerage desk, fundamental long/short hedge funds lost 1.3% on Thursday, a two-standard-deviation event; tech-focused funds fell more than 4%, nearly erasing their year-to-date gains. Momentum strategies suffered a 3.7-standard-deviation loss. Morgan Stanley data showed that the decline in total hedge fund leverage since its June peak was the largest in more than a decade.
Quantitative Liquidation Takes Over, Systematic Selling Pressure Self-Reinforces
Once the market decline was established, a series of quantitative trading mechanisms were triggered, pushing selling pressure to a new magnitude.
Charlie McElligott, managing director of cross-asset strategy at Nomura Securities, estimated that during Thursday's session, options dealers' negative gamma exposure was about $7 billion for every 1% market move—meaning for every 1% decline in stocks, dealers needed to sell an additional $7 billion of stocks to hedge risk. At the same time, volatility-control funds needed to sell about $61 billion of stocks, of which $25 billion came from liquidation not completed on Wednesday; leveraged ETF closing rebalancing would contribute another roughly $47 billion of selling.
Trend-following quantitative funds (CTAs) were also retreating in tandem. According to Vanda estimates, CTAs sold a combined total of about $13 billion in S&P 500 and Nasdaq futures, with positions falling to near historic lows.

Barclays estimated that volatility-control funds cut equity exposure by 30 percentage points in a single day, the largest one-day reduction since the February 2020 COVID shock. "Conversations with clients tell me they have a stronger incentive to reduce this risk further at this point," McElligott wrote. "The feedback theme is: preserve what little is left of year-to-date gains, and live to enter next year's new capital and new risk cycle."
By 3 p.m., the Nasdaq was down 4.5%, and some traders were still hoping for a rebound in the final hour. Instead, selling intensified, and the S&P 500 closed near its low of the day, recording its largest single-day decline since April last year.
AI Sector Liquidated, Damage Concentrated and Deep
The destructive force of this selloff was highly concentrated in AI-related sectors.
Sub-sectors such as memory chips, optical networking, data centers, and AI semiconductors fell 12% to 15% in a single day, representing extreme moves of five to six standard deviations. About a dozen AI stock baskets all posted their worst single-day performance since ChatGPT's launch in November 2022. Among them, the hardest-hit memory and optical communications baskets have been cut in half from their June highs, exceeding any pullback in the past four years.
As of Thursday's close, 57% of Nasdaq 100 constituents had fallen more than 20% from their highs—a proportion even higher than when the index itself entered a bear market in March 2022.
Part of what made this crash so dramatic is that it erupted almost out of calm. The VIX was just 16.6 points at Thursday's open, below its one-year average; by the close it was near 28. Since 1980, the S&P 500 has fallen more than 2% the day after rising 1.5% only 48 times, almost all during bear markets or crises.
Political Shock Compounds Old Worries, AI Narrative Faces Repricing
The market's violent reaction reflects investors' deep-seated anxiety about the AI investment thesis.
Before the election, the market already harbored doubts about the sustainability of the AI trade: tech giants' capital expenditures kept swelling, cash reserves were shrinking, and debt was piling up on data center operators' balance sheets. The Democratic victory added a new layer of political risk—the Democratic Party's strong opposition to data center expansion, especially in states such as Texas, Ohio, and Georgia that have become key battlegrounds for data center construction, casting a shadow over the prospects for AI infrastructure buildout.
BofA analyst Michael Hartnett noted that among surveyed voters, as many as 76% oppose building new data centers near their communities, which is becoming a severe obstacle to AI infrastructure expansion.
Matt Rowe, senior portfolio manager at Man Group, said the election results provided "quantifiable evidence that there is genuine public antipathy toward data center construction," which "is starting to change my judgment about the probability of these projects coming to fruition." "All else equal, these projects will take longer to advance and will cost more."
Joe Gubler, portfolio manager at Causeway Capital Management, noted that "there will always be losers, and not everyone betting on capital expenditures can be a winner."
On the other side, investors who exited early avoided the storm. Jeff Muhlenkamp had nearly emptied his fund's entire AI holdings before the plunge; his $275 million portfolio has been roughly flat since November and has outperformed the S&P 500 for the year. "We sold what was expensive and popular and bought what was cheap and forgotten," he said. "When momentum turned, we benefited."
The Market Searches for a Way Out
As the AI trade is liquidated, investors are looking for new safe havens—but the road is not smooth.
Even before the election, money had begun rotating into lower-valuation defensive sectors such as utilities and consumer staples. In October, growth stocks underperformed value stocks by 10 percentage points, the largest monthly gap since 2001. Yet Thursday's plunge showed that these new favorites also failed to withstand the shockwave from the tech selloff.
Some investors, having positioned themselves early, were able to walk away unscathed. Fund manager Jeff Muhlenkamp had cleared out almost all AI holdings before the plunge; his $275 million portfolio was basically flat in November and has outperformed the S&P 500 year to date. "We sold the expensive and popular and bought the cheap and forgotten," he said. "When momentum turned, we benefited."
On Friday, chip stocks rebounded first, with the Nasdaq 100 briefly recovering more than 2.6%, but major stock indices still ended the week lower, with the S&P 500 down 2.68% for the week. Sinisa Sorgic, a veteran trader at Bright Trading, shorted TSMC's U.S. shares that day but was "burned" as the stock rebounded more than 7.8% intraday. He summed up the week's feeling: "Yesterday was a bloodbath. The market is so crazy now that I simply don't dare go all in to buy the dip."
Divergence in the market has already emerged. Mateyo of Key Private Bank believes state-level regulations will delay but not stop data center construction, and public skepticism about AI may gradually fade as actual usage becomes more widespread. Casaletto of Wellington Management is more cautious, believing that the trend of slowing AI expansion has already taken hold.
Whether this storm is a violent shakeout in the middle of the AI bull market or the beginning of a deeper cyclical shift, Wall Street has yet to reach a consensus. But one reality is already clear: when political winds and crowded positioning turn at the same time, the buffer the market can offer is far thinner than imagined.